All You Need to Know About the FBT Exemption for Non-Electric Vehicles
Posted 4 Feb
Posted 4 Feb
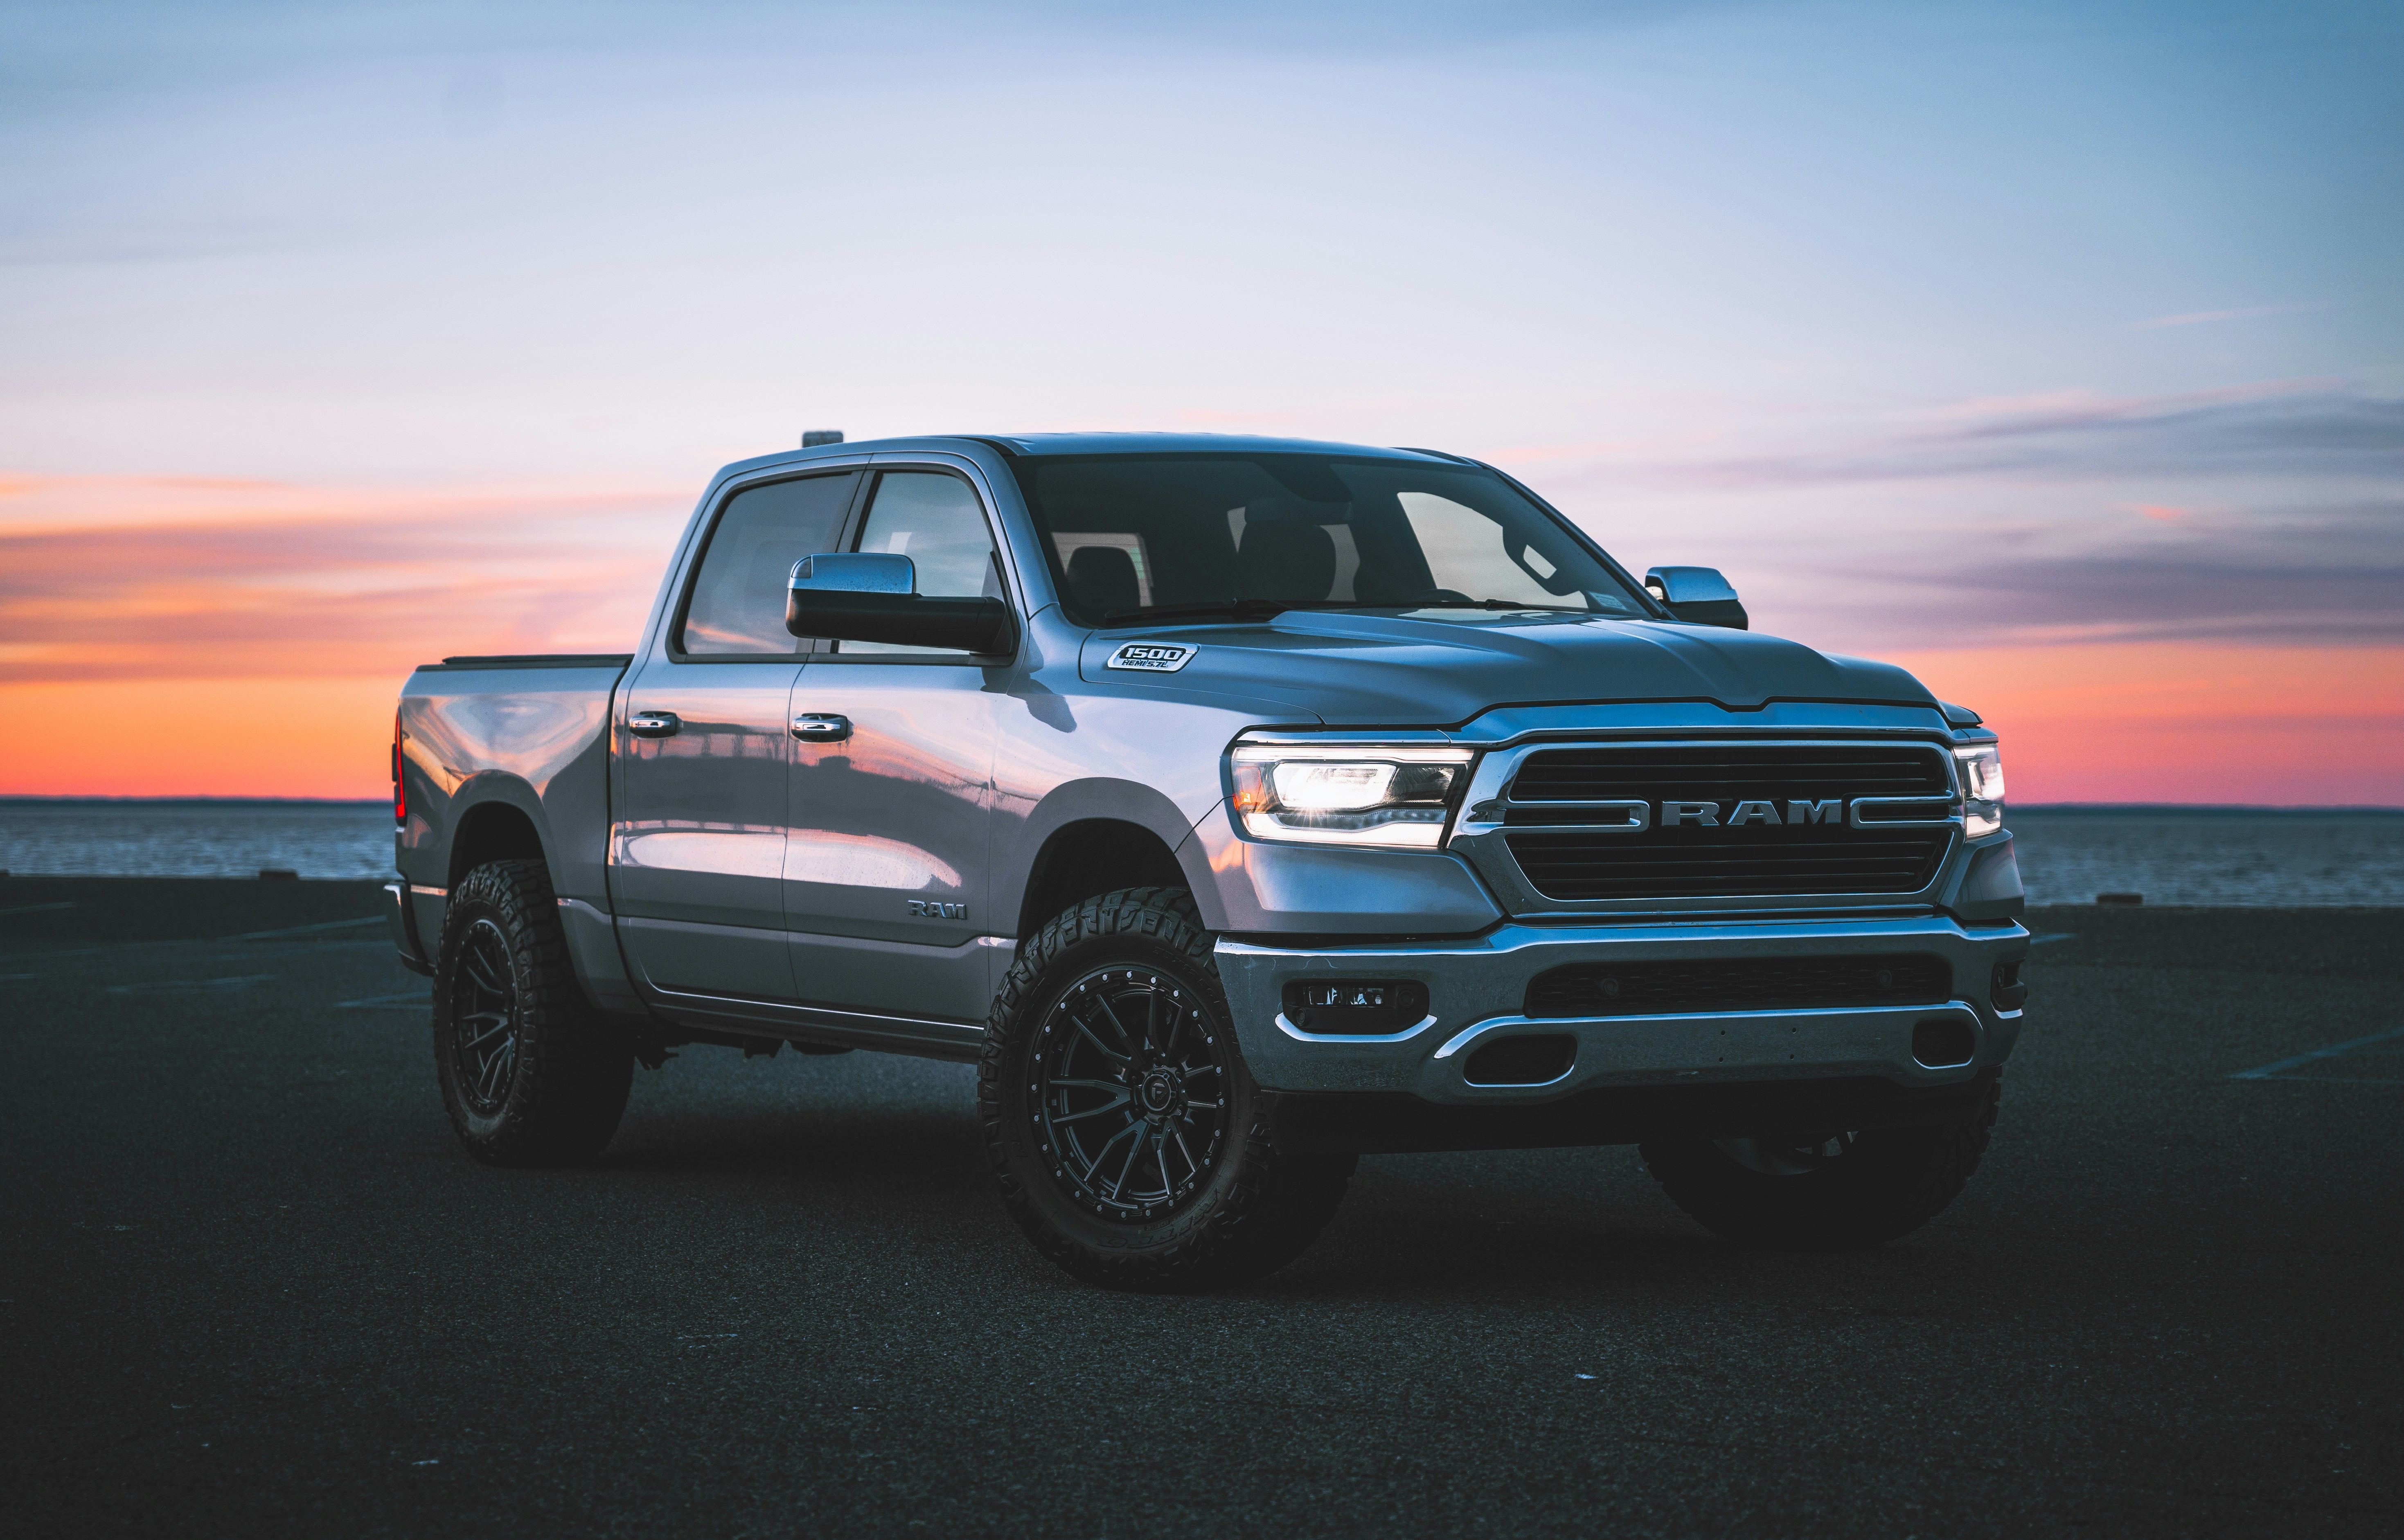
Many small businesses provide company vehicles for employees to perform their duties. However, what often goes unnoticed is that providing these vehicles may trigger Fringe Benefits Tax (FBT) obligations; especially if the vehicles are available for any private use. To help business owners avoid costly mistakes, this blog explains how to legitimately document vehicle usage to either quality for exemptions or avoid having to pay Fringe Benefits tax on company provided vehicles.
If you’re providing commercial vehicles such as utes, panel vans, or four-wheel drives, certain criteria under ATO Practical Compliance Guideline PCG 2018/3 must be met to qualify for an exemption.
| Criteria |
Explanation |
| The vehicle is an eligible vehicle. |
Includes certain utes, panel vans, and four-wheel drives not principally designed to carry passengers. The ATO lists eligible dual cabs,
single cab utes, and vans under MT2024A. |
| The vehicle is provided to a current employee for work-related duties. |
Maintain a detailed logbook reflecting work-related usage. |
| The vehicle’s GST-inclusive value is below the luxury car tax threshold. |
For FY 2025–26: $80,567 for non-EVs and $91,387 for EVs. |
| The vehicle is not part of a salary packaging arrangement. |
The employee cannot choose extra pay instead of the vehicle. Your company’s FBT Policy should reflect this. |
| Private use is limited. |
Employers must have a written policy limiting private use and obtain an employee declaration confirming this. |
| Home-to-work travel is allowed, but private detours must be minor. |
Any detour must not add more than 2 km to the usual route. |
| Wholly private journeys must be minimal. |
Employees must not exceed 1,000 km in total private travel per FBT year or any single private trip exceeding 200 km (return). |
While maintaining a logbook isn’t mandatory, it’s highly recommended. In an audit, the ATO often requests logbooks and declarations as
evidence of limited private use.
If your business provides non-commercial vehicles or shared office vehicles, the rules are even stricter.
| Criteria |
Notes |
| The vehicle must not be available for private use. |
Keys should be kept at the business premises. The car should not be garaged at an employee’s home. A company FBT Policy and employee
declaration must reflect this. |
| The vehicle is only used for work-related duties. |
Maintain a clear logbook and internal FBT Policy outlining this restriction. |
| Odometer readings must be recorded at the start and end of each FBT year. |
Ensure odometer readings are captured on 1 April and 31 March annually. |
Mobile apps like Driversnote to record trip details accurately and ensure compliance with ATO documentation requirements.
Even with the best intentions, many businesses inadvertently fall into FBT traps. Here are the most common:
• Providing employees with “exempt” vehicles but allowing unrestricted private use.
• Failing to retain signed employee declarations limiting private use.
• Missing or incomplete logbook entries.
• Forgetting to update policies annually or at vehicle replacement.
• Assuming that simply being a commercial vehicle guarantees exemption.
FBT can be a complex and easily misunderstood area of tax. Without proper understanding and documentation, small business owners risk
incorrect FBT treatment and unexpected tax liabilities.
By keeping thorough records, maintaining a compliant company vehicle policy, and ensuring employees meet the exemption conditions, your
business can legitimately enjoy FBT exemptions while staying fully compliant with ATO requirements.
Contact Empire Accountants for advice on FBT compliance and vehicle policy reviews. We’ll help you minimise risk, ensure correct FBT reporting, and make the most of your legitimate exemptions.
Starting a company is an exciting step, but the order in which you register your business and make purchases can affect your GST claims. If you have paid for equipment or start-up expenses personally before your company was incorporated, you may be wondering whether those GST credits are lost.
Starting a business can be equally exciting and daunting. What may have begun as a side hustle can grow into something much bigger - and
eventually, you may reach the point where doing everything yourself is no longer sustainable.
For many small business owners, that next stage of growth brings an important question: should you hire your first employee or engage an
independent contractor?
For many small business owners, a new car is both a practical business tool and a significant financial commitment. One of the first questions we are often asked is: “Should I buy the car through my company, or should I own it personally?”